
Dental And Vision Insurance: Key Considerations For Small Business Owners

Enrollment mechanics, eligibility, tax considerations, and comparing plan limits for small business owners
Enrollment mechanics address when and how employees may join dental and vision plans, including initial eligibility, waiting periods, and qualifying life events that trigger mid-year enrollment. Employers often set eligibility based on hours worked or employment status, and carriers may require specific documentation. Open enrollment periods allow for annual plan selection or changes; understanding these timelines helps ensure compliant administration and consistent coverage. Clear enrollment rules may reduce interruptions in employee access to routine services.
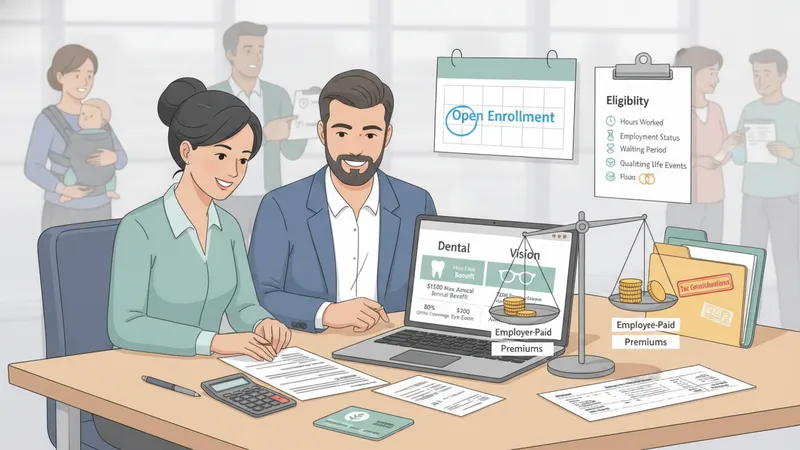
Tax considerations can affect plan design and employee contributions in jurisdictions where payroll tax treatment differs between employer-paid and employee-paid premiums. In some systems, employer-paid group premiums may be deductible for the employer and treated favorably for employees’ taxable income, while voluntary employee-paid premiums may be handled differently. Account-based vehicles like FSAs or similar arrangements may permit tax-preferred payment of eligible dental and vision expenses, though rules vary by location and regulatory framework, so prudent consultation is advised.
Comparing plan limits requires attention to annual maximums, lifetime limits, frequency limitations (for example, exam or frame replacement intervals), and exclusions. Some dental plans impose lifetime orthodontic limits or age-related restrictions; vision plans may limit the frequency of lens replacements. When comparing options, it can be helpful to tabulate these limits alongside premium implications to present a clear view of likely coverage in routine and higher-cost scenarios. Such comparisons may reveal which plan features most directly affect employee out-of-pocket exposure.
Documentation and communication are practical elements that often determine whether employees can use coverage effectively. Providing accessible summaries of benefits, examples of typical cost-sharing for common services, and clear instructions for finding in-network providers may reduce confusion. Employers may also consider periodic reviews of plan performance metrics—such as utilization rates, claims experience, and employee feedback—to inform future plan selection and design adjustments, recognizing that changing workforce needs can influence the relative value of different plan features over time.