
Financial Advisory Services: Understanding Core Functions And Professional Roles

Operational practices, fee structures, and review processes in financial advisory services
Operational practices in advisory firms commonly include client onboarding, documentation of objectives and constraints, compliance monitoring, and periodic performance reporting. Onboarding often involves disclosure of services, fee schedules, potential conflicts of interest, and a written engagement agreement. Firms may maintain formal policies for recordkeeping, confidentiality, and business continuity. Clear operational processes help ensure that advice is consistently applied and that review mechanisms exist to detect mismatches between stated objectives and implemented actions.
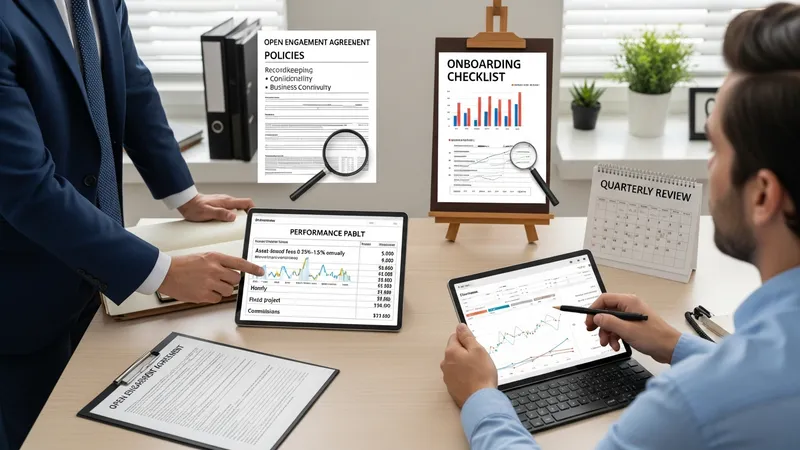
Fee structures vary and may include asset-based fees (a percentage of assets under management), hourly billing, fixed project fees, or commissions tied to specific products. Asset-based fees commonly range from approximately 0.25% to 1.5% annually in many markets, while hourly or flat planning fees can vary from modest amounts to several thousand in local currency depending on complexity. Each fee model has implications for perceived incentives and for the types of services prioritized; transparent disclosure of fees and services is a standard practice to support informed client decisions.
Review processes typically include scheduled portfolio and plan reviews—often annually or semiannually—with additional reviews triggered by major life events. Reviews generally reassess assumptions, measure progress toward goals, and document any changes to objectives or risk tolerance. Performance reporting may show returns relative to benchmarks, attribution analyses, and summaries of transactions. These reviews function as governance checkpoints to ensure continued relevance and to document rationale for any material adjustments.
Practical considerations for clients and advisers include maintaining clear communication channels, agreeing on measurable objectives, and setting realistic review cadences. Advisors often recommend establishing an emergency cash buffer and documenting succession plans for continuity of advice. Such considerations are offered as prudent planning practices rather than guarantees, and they are typically tailored to the client’s circumstances and preferences during the onboarding and review process.