
Inventory Management System: Core Features, Functions, And Workflows Explained

Inventory Management System: Purchase, Receiving, and Supplier Workflows
Purchase and receiving workflows link procurement activity to inventory records. Typical systems record purchase orders, expected arrival dates, and planned quantities so that receipts can be matched to orders and invoices. Matching procedures—three-way match between purchase order, receipt, and supplier invoice—are common controls to verify that inventory costs are recorded only for goods actually received. Receiving workflows often include inspection steps to capture damaged or nonconforming items and to create appropriate adjustment or return records.
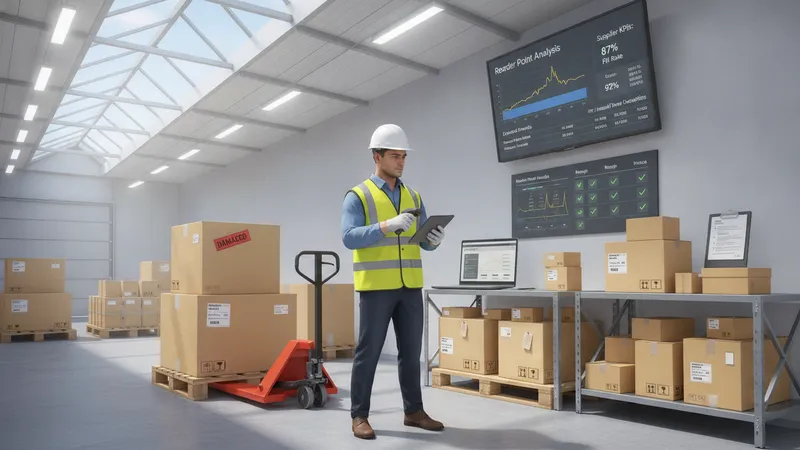
Lead time management and supplier variability are central to replenishment calculations. Systems may store supplier lead-time averages and variability measures to inform reorder points and safety stock. Where lead times are volatile, teams may opt for higher safety stock or more frequent review intervals. Supplier performance metrics, such as on-time delivery rates and fill rates, are often tracked in reporting modules to inform sourcing decisions and to highlight areas where expectations or processes may need alignment.
Goods receiving typically involves physical checks for quantity and condition, barcode or RFID tagging where required, and immediate system updates to reflect available stock. Putaway logic then assigns storage locations based on item attributes, turnover, and available space. For serialized or batch-controlled items, receiving workflows usually capture unique identifiers and expiration dates to support traceability and compliance requirements, especially for regulated goods.
Integration points between procurement, receiving, and finance are commonly required so that inventory movements trigger appropriate accounting entries. Systems may support staged receipt statuses—such as received-but-not-inspected or received-and-accepted—to prevent immediate cost recognition until quality checks are complete. Clear rules about when costs and liabilities are recorded typically improve the alignment of operational records with accounting requirements.