
Pension Options For Seniors: Understanding Key Retirement Income Choices

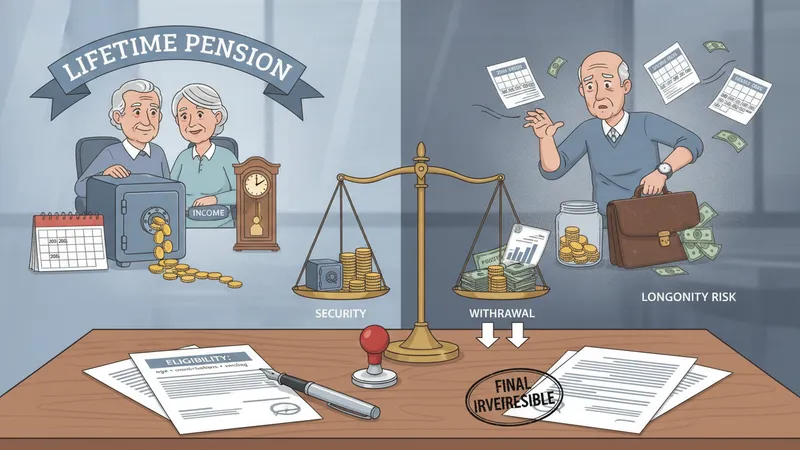
Eligibility and payout structures for pension plans and income products
Eligibility criteria for pensions typically include age requirements, contribution history, and minimum service periods. Some systems permit reduced benefits for early claiming, while others allow delayed retirement credits that increase later payouts. Vesting rules in occupational plans determine whether a worker retains rights to employer-provided benefits after changing jobs. For account-based plans, eligibility may not be restrictive, but access rules and tax treatments often depend on age or other qualifying events. Understanding these conditions is important when assessing expected income timing and amounts.
Payout structures can be periodic lifetime payments, joint-and-survivor options, lump-sum distributions, or flexible withdrawals from accounts. Lifetime pension options provide income continuity but may reduce access to principal. Lump-sum withdrawals offer liquidity and control but require active management to avoid longevity shortfalls. Joint options may reduce the initial payment to provide survivor protection. These structural choices typically reflect trade-offs between income security and flexibility, and they are often irreversible once selected.
Communication clarity is a practical consideration: plan documentation should specify how benefits are calculated, whether payments are indexed for inflation, and the mechanics of survivor benefits. Where formulas apply, they may reference final or career-average earnings, multipliers, and service credits—each altering the benefit profile. When considering conversion of account balances into income, transparent information on fees, assumptions about life expectancy, and surrender provisions can materially affect the net income realized over time.
As an insider consideration, it can be helpful to request personalized benefit estimates and scenario tables from plan administrators or insurers, showing alternative claiming ages and payout forms. These estimates often illustrate how small timing differences can change lifetime income amounts. This information supports comparison across sources and informs choices about sequencing, deferral, and partial conversions.