
Profit And Loss Software: How Small Businesses Can Track Income And Expenses

Data input methods and maintaining record accuracy
Methods for entering revenue and expense data vary from fully manual entry to automated feeds and scanned-receipt workflows. Manual entry is straightforward for low transaction volumes but can increase the risk of data-entry errors as activity grows. Automated bank and payment feeds can populate transactions more quickly, though payee names and descriptions sometimes need human review to ensure proper categorization. Receipt scanning with optical character recognition (OCR) may capture amounts and dates but often requires verification, particularly for vendor names and tax-related fields. Combining methods can balance speed with oversight.
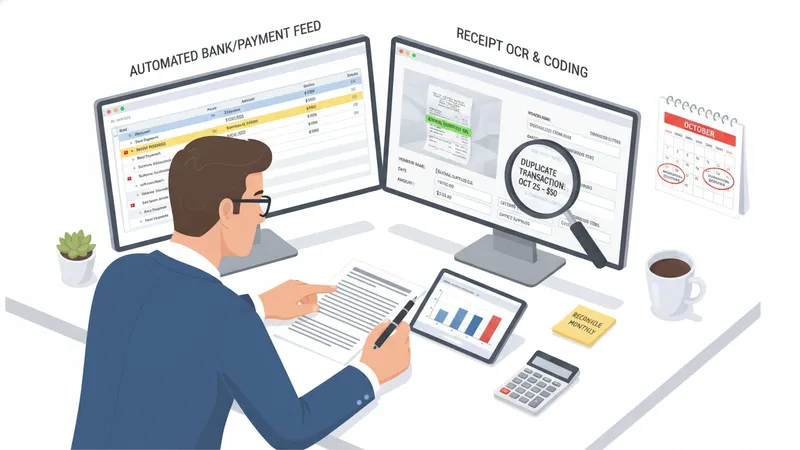
Reconciliation practices are central to accuracy. Regularly comparing the software’s transaction list to external statements—bank, merchant, or payment processor—helps identify missing items, duplicate entries, or misclassified transactions. Reconciliation workflows may include clearing entries, marking matched transactions, and recording adjustments for bank fees or timing differences. Establishing a cadence for reconciliation, such as monthly or quarterly, typically reduces the accumulation of unresolved discrepancies that can distort profit-or-loss reports.
Maintaining a clear audit trail supports confidence in reported results. Systems that log who created or edited entries, with timestamps and notes, make it easier to trace changes and understand prior-period adjustments. When corrections are necessary, keeping notes and preserving original entries rather than overwriting history can aid later review. For small businesses that engage external advisors periodically, readable audit trails and exported transaction lists simplify third-party reviews without requiring re-entry of historical data.
Common accuracy challenges include inconsistent categorization, uncaptured petty transactions, and timing differences between cash receipts and recorded revenue under accrual accounting. Addressing these challenges often involves standardizing category mappings, capturing small expenses through regular batching or expense policies, and clarifying the chosen basis (cash versus accrual) for reporting. Such practices may reduce ambiguity in period results and support clearer interpretation of operating performance.