
Small Group Health Insurance: Key Coverage Options For Employers And Teams

Plan Types and Coverage Structures in Small Group Health Insurance: Key Coverage Options for Employers and Teams
Plan types for small groups commonly include managed care models, open-network models, account-compatible plans, and alternative funding arrangements. Managed care models emphasize coordinated care within a defined network, which may reduce routine costs. Open-network models allow broader provider choice but can increase the variability of claims costs. Account-compatible plans pair higher cost-sharing with a dedicated account that members may use for qualified expenses. Level-funded or self-funded arrangements shift certain financial risks to the employer while often including stop-loss features to limit exposure. Each structure organizes coverage around differing balances of network control, member choice, and predictable costs.
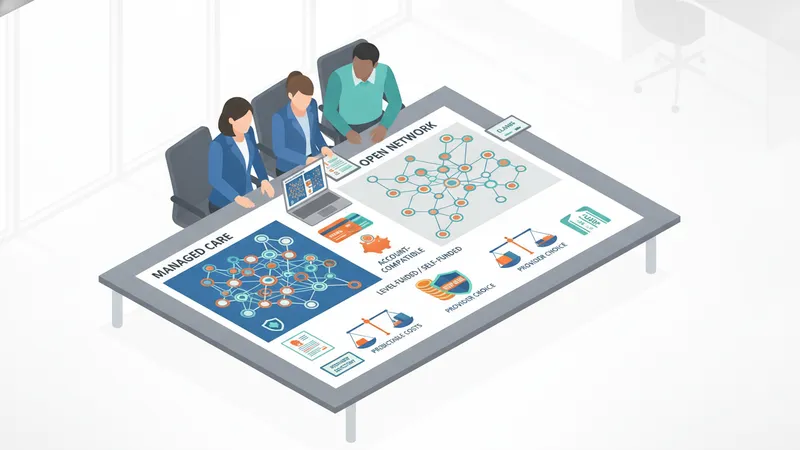
Network design is a core structural feature that may affect utilization and member satisfaction. Narrower networks can deliver lower negotiated rates with participating providers and therefore influence premium levels or employer contribution choices. Broader networks offer more provider options but may include higher negotiated rates and greater administrative complexity in claims adjudication. Network adequacy, referral requirements, and out-of-network benefit rules often determine practical access to care for employees. Employers commonly review provider directories and typical utilization patterns when assessing network suitability for their workforce.
Formulary design and prescription coverage are often integrated into plan structure and can materially affect member cost-sharing. Plans may use tiered formularies that vary cost-sharing for generic, preferred brand, and specialty medications. Prior authorization and step therapy protocols can manage utilization of high-cost treatments, while mail-order options may influence ongoing drug costs. These elements interact with deductible and out-of-pocket policies; for example, some plans apply prescriptions to the medical deductible while others use separate pharmacy cost-sharing. Employers may consider typical prescription profiles in their employee population when evaluating formulary features.
Provider payment mechanisms and administrative arrangements impact plan operation and predictability. Fee-for-service payment with negotiated rates is common, but alternative provider payment models such as bundled payments or value-based contracts may appear in certain markets and networks. Administrative capabilities—claims processing speed, reporting detail, and member support—affect the employer’s operational burden. When evaluating coverage structures, employers may examine historical reporting, projected claims methodologies, and the presence of cost-containment programs such as utilization review or care management as considerations rather than assurances of specific outcomes.