
Dental And Vision Insurance: Key Considerations For Small Business Owners

Dental and vision insurance for small business owners describes benefit options that cover routine and restorative oral care and eye care services for employees. These insurance arrangements may be offered as employer-sponsored group plans, voluntary individual products that employees purchase through payroll, or standalone individual policies secured outside the workplace. Key considerations typically include the types of services covered (preventive, basic, major for dental; exams, lenses, frames for vision), cost-sharing mechanics, provider networks, enrollment rules, and how coverage interacts with other employee benefits.
When evaluating dental and vision insurance, small business owners often weigh plan design against budget, workforce needs, and administrative capacity. Plan choices can influence employee access to preferred providers and the predictability of out-of-pocket costs. Some plans emphasize preventive care with low or no copayments, while others structure benefits around annual maximums, waiting periods, or staged coverage for major services. Understanding these structural elements may help owners match plan features to typical employee utilization patterns without prescriptive recommendations.
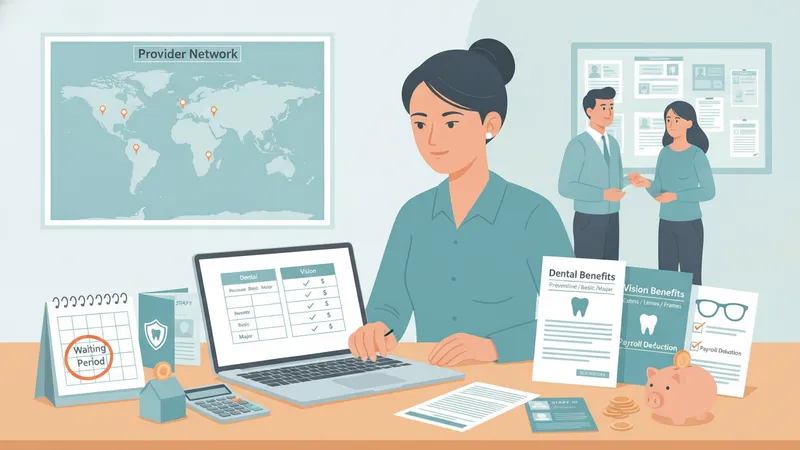
- Employer-sponsored group dental plans — Group policies that may cover preventive, basic, and major dental services; cost-sharing structures and employer contribution levels can vary by insurer and plan design.
- Individual dental insurance plans — Standalone policies purchased by individuals that may be suitable when an employer does not offer group coverage; benefits and premiums typically differ from group plans.
- Group vision plans — Commonly include routine eye exams and allowances for corrective lenses or contact lenses, sometimes offered as a separate employer-sponsored benefit.
- Voluntary or employee-paid supplemental plans — Options funded largely by employee payroll deductions that may provide limited coverage for services not included in a core employer plan.
Coverage structures for dental and vision plans often use categorical tiers such as preventive, basic, and major dental services, and routine exams versus corrective lenses in vision plans. Preventive dental care commonly includes exams, cleanings, and simple X-rays; basic and major categories may include fillings, root canals, crowns, and prosthodontics, often subject to waiting periods or staged benefit percentages. Vision benefits typically separate diagnostic services (eye exams) from elective products (frames, lenses, contacts), with dollar allowances or discounts. Understanding these tiers can clarify which services are likely to be covered and under what cost-sharing terms.
Cost-sharing elements—premiums, deductibles, copayments, and annual or lifetime maximums—can influence both employer budgeting and employee out-of-pocket exposure. Employers may pay a portion of premiums for group plans and set employee payroll contributions; voluntary plans can transfer most premium costs to employees. Deductibles may apply to certain dental services but are less common for routine vision exams. Some dental plans apply percentage-based coverage (for example, preventive at near-full coverage, major services at a lower percentage) and may include annual maximum benefit limits that cap insurer payouts.
Provider network design is an important operational consideration. Some dental plans use a preferred provider organization (PPO) model that allows access to a broader range of dentists with varying reimbursement rates, while dental health maintenance organizations (DHMO) or managed care networks may restrict choices but offer lower cost-sharing. Vision plans often rely on national vision networks or local optical providers with set fee schedules or product allowances. Network size, out-of-network reimbursement levels, and ease of locating in-network providers can affect employee satisfaction and utilization.
Administrative factors such as enrollment windows, eligibility rules, waiting periods, and claim processing times may affect the practical value of dental and vision offerings. Small employers often face trade-offs between simpler plan administration and more flexible coverage options. Pre-enrollment communication about benefits, provider directories, and typical cost responsibilities may help employees make informed use of their coverage. The next sections examine practical components and considerations in more detail.